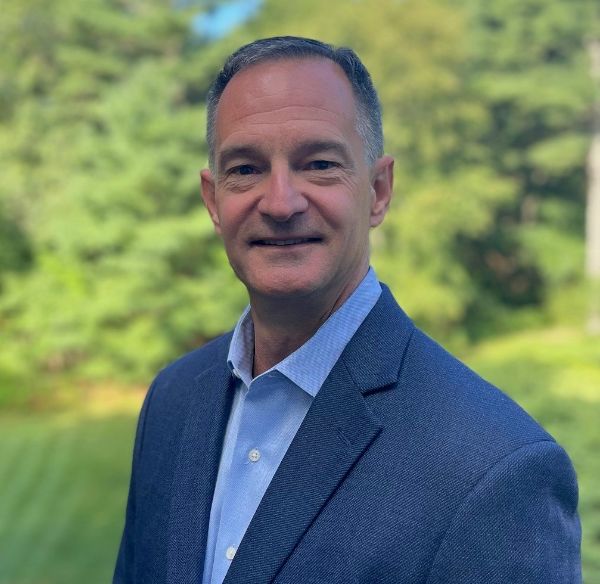
Chris DiCenso has spent much of his career helping firearms and shooting sports companies grow. Most recently CEO of SDS Arms, he previously served as president of Camfour and founded Growth Strategy Partners, a consulting firm that has worked with companies including Beretta, Benelli, CZ-USA, SureFire and STI/Staccato.
Now returning to consulting, DiCenso brings a perspective shaped by experience in manufacturing, distribution and executive leadership, along with his own involvement in the shooting sports as an active competitor. QA Outdoors caught up with DiCenso to talk about the state of the firearms business, the challenges and opportunities facing companies today, and what he sees coming next.
QA Outdoors
You've led an importer, a distributor and a consulting firm serving manufacturers across the firearms industry. From those different vantage points, what are the best-run companies doing right in the current business climate?
Chris DiCenso
I'm going to add my experience prior to that. I was a consultant for many years, and what owners asked me was, “How do you grow your business?” Being an engineer, I didn't have the formula—the science behind it—so I did a lot of research to identify what successful companies do, regardless of the environment.
The short answer is that they do the basics very, very well. My research identified what I ended up calling the seven keys to growth—basically, seven fundamentals. I learned that a lot of companies just don't apply those fundamentals.
Successful companies, regardless of the environment, apply the fundamentals and do them very well. One of those fundamentals is having a good strategic plan and executing it well. If your environment changes and you apply that principle well, you'll recognize that something has changed and adjust accordingly.
QA Outdoors
You recently wrote in a piece for our Weekend Edition that flat firearms demand may actually be good news because it could mean the industry has finally reached the bottom of the post-COVID decline. What should companies be doing now to prepare for the next growth cycle?
Chris DiCenso
Product innovation typically drives sales. People look at the upside—the business going up—and think, “Great, we're going to have a good future.” All that's doing is floating everybody's boat.
To me, competition comes back to how well you're performing versus everybody else. During COVID, when a company told me, “We grew 25% last year,” I would say, “Oh, that's too bad. The industry was up 50%.” It's all relative.
If we're entering a growth market—and you can throw the election into it, although I'm not a big fan of relying on that to drive growth—any company that wants to outperform the competition needs to do the fundamentals better. Some of that involves marketing and investing in product innovation.
You need to have a differentiated product and let people know you have a differentiated product. Those are things companies often don't do very well. Basically, create differentiation and articulate that differentiation. Whether we're coming out of a downturn or entering a period of growth, get more aggressive, but define how your products or services are differentiated. Most aren't differentiated very well, and that's why they don't sell.
QA Outdoors
How many companies are still operating as if the pandemic-era surge in demand will return, and what mistakes are they making because of that assumption?
Chris DiCenso
I don't get the sense that any of them are operating as if the pandemic [demand] is going to come back. I think everybody, even outside the shooting sports industry, is in wait-and-see mode: Let's see what happens.
I'm going to go back to research showing that you can grow in a down economy. You just have to get a little more aggressive and do the fundamentals even better. I think companies are pausing right now. They're waiting to see, and that's why they aren't going to grow.
If they keep playing the wait-and-see game—waiting for some regulatory change or a surge in demand—they're just going to float like everybody else. They'll grow like everybody else, but they won't perform any better.
QA Outdoors
You rely on data from sources such as NSSF Adjusted NICS, NASGW SCOPE and retail business-intelligence platforms to evaluate the market. Are enough firearms companies making decisions based on reliable data, or are too many still managing by instinct and anecdote?
Chris DiCenso
Way too many are managing by instinct and anecdote. Larger public companies, or simply much larger companies, tend to be more formal and use more data. But when you get into small and midsize companies—I've seen dozens of them in the industry—they aren't using data.
When I talk to NASGW, particularly about its SCOPE database, I hear that not many people are using it, and that's kind of sad. My teams have had great success looking at market share and inventory data. This goes back to comparing your performance with a benchmark.
For example, if I had 11 weeks of inventory on hand while the industry had nine, that highlighted the fact that I had too much inventory. That's at the macro level. You still have to bring it down by product and SKU, but companies definitely need to use more data.
I just don't think they know how.
QA Outdoors
Industry-wide numbers can hide significant differences between product categories, price points and individual SKUs. What should executives be measuring before deciding where to invest—or where to cut back?
Chris DiCenso
There's always a debate over whether to look at top-line sales dollars, gross-margin dollars—which are calculated after the cost of goods sold—or operating-profit dollars, which are much harder to obtain because they require cost allocations.
The first thing companies should do is understand where they're making money. I tend to believe companies should focus on gross-margin dollars—not gross-margin percentage—because gross-margin dollars are what pay for everything.
The first thing I would suggest is identifying which products generate the most gross-margin dollars. I have yet to see a company do that correctly.
QA Outdoors
Why do you think that is?
Chris DiCenso
They don't understand it. This isn't limited to the shooting sports industry; I've worked outside it as well. Privately held companies are often run by entrepreneurs, and entrepreneurs are phenomenal at starting and growing businesses. They have great ideas. They generally aren't known for being operationally strong or for operationalizing what they've created.
That operational piece includes understanding costs. At nearly every company where I've examined the income statement, it was a mess. It wasn't organized or categorized properly; it was either too detailed or didn't contain enough detail. If you don't know where your costs are, you can't understand where your profits are.
This goes back to the science of running a business and doing the basics very well. Having a good income statement isn't that difficult, but a lot of companies simply don't focus on it.
QA Outdoors
You’ve advised companies to shorten the historical windows they use to forecast demand. What are the dangers of relying on six-month or annual averages in a market that can change quickly because of politics, regulation or consumer sentiment?
Chris DiCenso
The longer the window, the more likely you are to get an average that's polluted by historical data that is no longer relevant. You're going to miss short-term changes.
We went through this at the last company I was with. If you looked at a four-week window, things could change in two or three weeks, if not four. But was that change an indication of a trend, or was it just an anomaly or a spike? If you expand from four weeks to 16 weeks, you're going to get a different picture.
That's for regular demand. Then you overlay the seasonal demand we have, with summer slowing down and the third, fourth and first quarters picking up. We ended up looking at two windows. I believe one was a six-week window. Because we had some imported products, we had longer lead times on the supply side. Looking at two windows helped us see how much demand was actually changing.
Every company has to examine its supply chain and understand where replenishment is coming from. A manufacturer may sell to a wholesaler, which sells to a dealer, which sells to the consumer. There's a lot of inventory in that pipeline.
When you run an ad or do something else that creates consumer demand, the consumer goes to the retail store and the retail store goes to the wholesaler. If inventory in the pipeline is higher than usual, it will take longer for the manufacturer to receive that feedback. If there's less inventory, the feedback will come more quickly.
It's about understanding your supply chain and demand cycle so you can determine the right forecasting window for your company.
QA Outdoors
You’ve also advocated classifying inventory into A, B and C categories and assigning different service levels to each. If that is a relatively basic inventory-management discipline, why do so many companies still fail to implement it?
Chris DiCenso
ABC categorization is a basic concept that goes back to the 1950s or 1960s, if not earlier. It identifies A items as high-volume or high-dollar products. B items are in the middle, and C items are at the low end.
At Camfour, we had more than 20,000 items. You can't manage all of them weekly, so you look at what's important. A items are more important than B items, which are more important than C items. If you identify your A, B and C items, you can better manage your inventory and products overall—not just on the inventory side, but also on the buying and selling sides.
I'll give credit to my supply-chain manager at SDS Arms, who expanded ABC into D, E and F categories because we had new products coming in. A new product isn't really an A, B or C item because you don't have any history on it. I don't remember all the categories he used, but one was for new products and another was for discontinued products. Expanding the classification helped us tremendously with purchasing and inventory management.
Again, it comes back to basic fundamentals. There's no rocket science behind it. It's a basic principle that most companies don't apply.
QA Outdoors
For a company with a direct-to-consumer component, whether through its own website or something similar, does that same ABC categorization apply?
Chris DiCenso
It works for every company that has a product—toilet seats, candy, cigars, bourbon, you name it. If you have a product, you should be managing inventory, and ABC classification is a basic tool for doing that.
What comes to mind, Paul, is Microsoft Excel. Everyone uses a spreadsheet, but we probably use only 20% of its capabilities. Those who understand it better are more powerful and advanced, and they can do more with it. The business side is no different.
When you look at operations, there are a lot of fundamentals. To expand on inventory, you typically should decide on your fill rate: How often do you want to have a product in stock when somebody orders it? There's a science behind the percentage you apply and the amount of safety stock you want.
There's a lot of math—this is the engineer coming out in me. Inventory management and supply chain are all math. It's not a gut game or a feel game. You can make some adjustments, but it's mostly math. If companies used more math to manage their products and inventory, they would make more money.
QA Outdoors
Companies want to reduce inventory without losing sales because popular products are out of stock. How do the companies getting this right balance conserving cash with maintaining acceptable dealer and distributor fill rates?
Chris DiCenso
You just walked into that one, didn't you?
This gets back to understanding your supply chain and looking at weeks on hand. Most companies I've dealt with say they need to have $3 million, $5 million, $10 million or $15 million in inventory because that's what they've always had. But inventory levels really should be based on how many weeks of inventory you have in-house, and that weeks-on-hand calculation is based on demand.
That gets back to your earlier question: How many weeks of demand do you measure? Is it four weeks, five weeks, six weeks or seven weeks? What's the right number to provide enough warning that you don't run out of inventory because your time frame wasn't short enough—or carry too much because it was too long?
If companies adopt a weeks-on-hand perspective and add a fill-rate target—how often they want to have a product in stock—the likelihood of filling more orders will increase. That's especially important for A items. The A items will be the faster movers, while purchases of C items will decline. That means less cash sitting in inventory.
You'll sell more, increasing profitability, and potentially improve cash flow because you aren't stocking as many C items. Whenever I've conducted an ABC-classification analysis, a company's aged inventory has most often consisted of C items that weren't moving because the inventory wasn't being managed correctly.
QA Outdoors
Is that driven by fear, particularly at smaller companies, that “If I don't have it, I can't sell it,” so they keep inventory that's collecting dust and tying up cash just in case somebody calls for it? Is that why they're sitting on too much C stock?
Chris DiCenso
No. It's mostly because they don't measure it. Most companies have slow-moving-inventory reports, and sometimes the threshold is six months. At one company I worked with, an item wasn't considered slow-moving until it had been sitting for more than a year. I think I changed that to six months because I wanted to know early that it was slowing, not wait until it was moving so slowly that we couldn't get rid of it.
This goes back to weeks on hand. Companies don't know how to measure inventory velocity, so they don't really know whether they have too much or too little. I don't think anyone intentionally stocks a product just in case somebody buys it.
Most of the owners I've worked with like having a backlog. They want to have demand in the future, and that's actually a good thing. It's just a balance. Too much demand can cause you to lose orders if customers have to wait too long for fulfillment. It's a math problem. Companies aren't doing the math to determine what they should have.
QA Outdoors
Large companies generally have more capital, personnel and data at their disposal, but they can also be slower to react. What mistakes are larger companies making that smaller, more agile competitors can exploit?
Chris DiCenso
Smaller companies can introduce new products faster because founders face less bureaucracy. That's generally well known, and smaller companies can capitalize on it.
Smaller private companies may be less worried about reputation—or, more accurately, they're more willing to be aggressive in their marketing and in what they say and do. Larger companies typically don't do that.
But larger companies often have their supply chains figured out better than many smaller companies. When you're dealing with $5 million or more in inventory, you need to do a good job of managing it, and larger companies usually have dedicated supply-chain personnel. They're likely to execute the fundamentals better than smaller companies, but smaller companies can react more quickly because they don't have to work through the same bureaucracy.
QA Outdoors
Conversely, smaller and founder-led companies can make decisions quickly but may lack formal systems and experienced management. At what point does entrepreneurial instinct become an obstacle to further growth?
Chris DiCenso
I guess it's when they stop listening. One thing I saw as a consultant was that many team members who reported to owners weren't giving the owners feedback. They had offered feedback in the past, the owner ignored it and the team members eventually gave up.
When I became a president and CEO, I wanted to make sure I wasn't shutting people down. An owner, president or CEO may think he or she is correct, but it has been proven over and over that a team makes a better decision than an individual—unless that individual is the expert in that particular field.
If, as an owner, you aren't getting much feedback or pushback from your team, it's probably because they've tuned out after you've repeatedly shut them down.
QA Outdoors
I take it that's not a good thing.
Chris DiCenso
It's not a good thing at all. Founders and owners are phenomenal early on, and this isn't limited to our industry. The challenge I repeatedly hear about and see is that owners don't know how to let go. That's typical across every industry.
When I talk to bankers and investment bankers who sell companies, they tell me the owner is often responsible for so much that he or she can't disengage from the company. The owner is too involved and doesn't delegate.
That becomes a challenge when the owner tries to sell the company. The owner may be the key salesperson or control relationships with key customers. Because those responsibilities haven't been delegated, the owner can't leave.
It isn't just a short-term liability affecting annual decision-making or growth. When owners try to sell, they may be unable to exit, or it may take another year or two to build and empower a team that allows them to leave the company.
QA Outdoors
At SDS Arms, you increased sales, EBITDA [Earnings Before Interest, Taxes, Depreciation, and Amortization], employee engagement and the company’s Net Promoter Score. When a company needs to improve all four, where should leadership start—and which of those measurements do firearms-industry executives most often undervalue?
Chris DiCenso
First of all, we did that. That's what made the company successful. We had a really good team.
I always start on the financial side. When you increase the company's profitability, you have more money to invest in other things. As a consultant or operating executive, I'll first benchmark the EBITDA percentage—the profitability—and then work to improve it.
If you improve everything below the gross-margin line, every sale you bring in will be more profitable. I don't ignore sales, but I'm going to focus on the operational side and increase profits.
Actually, there are two things I would do: focus on profit and on what I'll call team building or culture. Get the team excited about where the company is going. Help them understand the vision and where they're going, and they can help you get there faster.
Profitability comes first, but you also need to work on the culture and build the team. The improvements you mentioned were the results, but my first priority was building the team. With the team in place, we could build the operations. Then we could build sales, the customer base and engagement.
QA Outdoors
How do you measure employee engagement when you're brought in to assess a company? How do you determine whether employee engagement is a serious pain point affecting performance?
Chris DiCenso
Anyone entering a company can get a sense of whether the culture is positive, neutral or negative just by talking to a few people. But I use formal surveys. There are standard employee-engagement surveys.
I like using the Best Places to Work survey. Business journals, such as the Boston Business Journal here in Boston, offer it, and Fortune publishes its own Best Companies to Work For list. The survey was developed by the Great Place to Work Institute.
I encourage companies to use surveys like these because they provide benchmarks. You don't just receive your own score; you can compare it with companies in your size category because the benchmarks differ for small, midsize and large companies.
At SDS Arms, the company had hired someone externally to conduct a survey in March, before I arrived, so we had a baseline. I repeated the same survey six months later.
QA Outdoors
I'll wrap up with a forward-looking question. During the next 12 to 24 months, what will separate the firearms companies that gain market share from those that merely survive—or disappear entirely?
Chris DiCenso
I have two thoughts. One answer would be to do more marketing and have good product differentiation. Any company can accelerate its growth over 12 to 18 months by spending heavily, if you will.
But what's more important is doing it repeatedly. It's not just a short-term sprint; it's a long-term marathon. The companies that succeed will do the basics very well, have an aligned team—which is very important—and execute well.
I mentioned my seven keys to growth earlier, but you need a good team, a good plan and strong execution. If you execute well, you'll discover what's working and what isn't.
Marketing is somewhat experimental. You're going to try different things, and some will work better than others. You can launch new products, but they won't all succeed. You can pursue new customers, but those efforts won't always succeed either.
The companies that execute better and faster will learn faster. They'll push harder on what works and move away from what doesn't.
I've never looked at growing a company by asking, “What's the market doing?” As a consultant, and later as a president and CEO, I've seen that if I can align a team, we can outperform the competition and win. That's always been my approach, and it has worked.
QA Outdoors
Chris, thanks very much for your time.